On 14 November 2026 the UK government said BT, M&S, Veolia and Home Bargains had signed up to offer payroll savings schemes to their staff. These schemes move a slice of your pay into a savings account before you have the chance to spend it. Here is how they work, what the evidence says, and what to check before you join one.
Key takeaways
- BT, M&S, Veolia and Home Bargains will offer staff payroll savings schemes, the UK government said on 14 November 2026.
- A payroll scheme moves an amount you choose from each pay packet into savings, and you can stop any time.
- Nest Insight trials found the highest participation when staff were enrolled automatically and could opt out.
- Before joining, check the account is in your name, withdrawals are free and quick, and the provider is FSCS-protected.
The short version
- A payroll savings scheme sends an amount you choose from each pay packet into a savings account. You can change the amount, stop, or take money out at any time.
- The government says more than half a million more UK workers will now have the chance to save this way. Tesco has also launched a scheme.
- These schemes are still rare. Only 7% of UK employers offered one, according to Department for Work and Pensions figures cited by the Financial Conduct Authority (FCA) in 2025.
- Sign-up design matters. Research by Nest Insight found the highest participation where staff were enrolled automatically and could opt out.
- It is a rainy-day pot, not a pension. Check that the account is in your name and whether the provider is covered by the Financial Services Compensation Scheme (FSCS).
What the government announced
The government announcement says BT, Veolia, M&S and Home Bargains have joined the National Coalition for Workplace Savings. Members agree to offer staff a payroll savings arrangement and to encourage them to use it.
Existing members named in the announcement include Co-op, SUEZ, Bupa, OCS, Mitie, Greene King, Burger King UK and Travelodge. Tesco is working with the coalition and has launched its own scheme.
The numbers need a careful read. The headline refers to “hundreds of thousands” of workers. The text says “over half a million more workers” will have the opportunity. Neither figure is broken down by employer, and having access is not the same as taking part.
The coalition came out of the government’s Financial Inclusion Strategy, published on 5 November 2025. Its own site says it is chaired by the Co-op and convened by the Money and Pensions Service (MaPS), the Centre for Inclusive Money at Nest, and The Investing and Saving Alliance (TISA).
How a payroll savings scheme works
The FCA describes the basic idea in its statement on workplace savings schemes. Agreed amounts of salary go automatically into “a readily accessible cash savings account.” In practice:
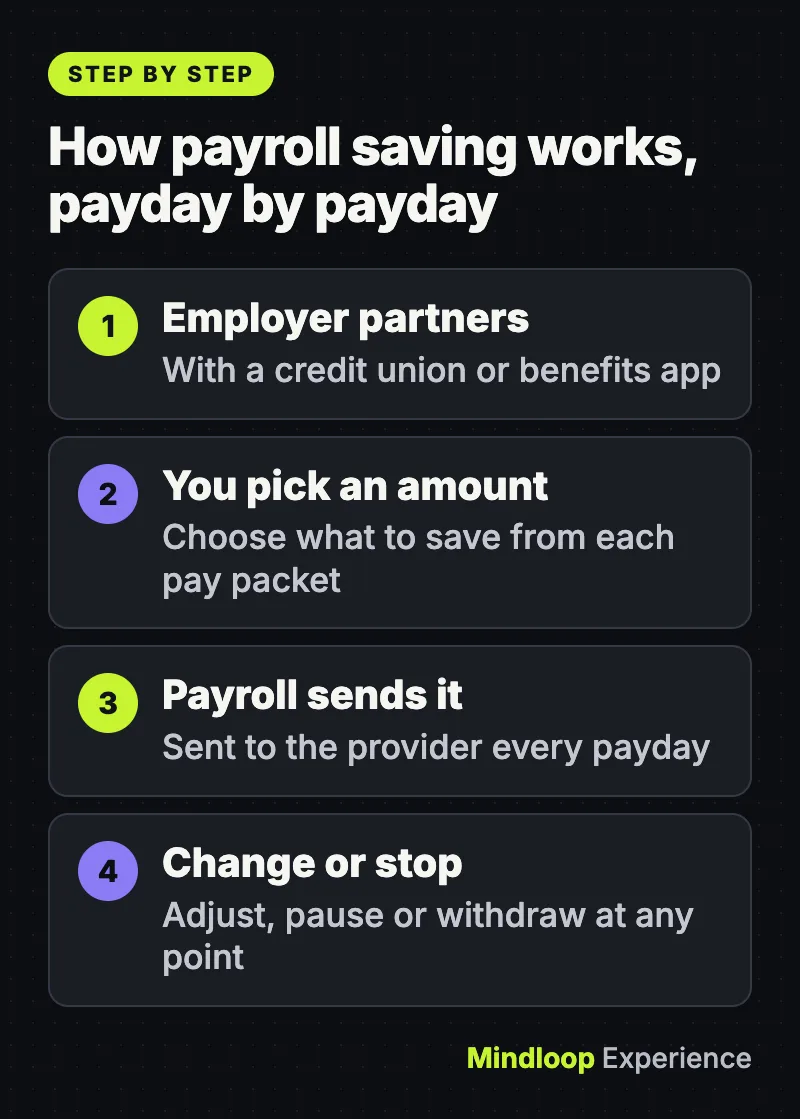
- Your employer partners with a savings provider. In the strategy’s examples, the provider is a credit union or the scheme runs through an employee benefits app.
- You choose how much to save from each pay packet.
- Payroll sends that amount to the provider every payday.
- You can change the amount or stop at any point. The government says savings in these schemes can be accessed “at any point without charge.”
There are two versions, and the difference matters.
| Opt-in | Opt-out (“autosave”) | |
|---|---|---|
| How you join | You choose to sign up | You are enrolled unless you say no |
| Can you leave? | Yes | Yes |
| Rules today | Works under existing rules, the FCA says | Wider use will likely need action from authorities, including possible changes to legislation |
Why saving straight from pay works
The Financial Inclusion Strategy calls payroll saving “a proven way of helping people start and maintain a savings habit.” It points to trials run by the research group Nest Insight, which found the highest participation where sign-up was automatic.
- SUEZ. New staff are signed up to save unless they opt out. Participation among new joiners is 48%, and they save an average of £40 a month with a credit union.
- Bupa Care Services and the Co-op. Both ran autosave through an employee benefits app. By month four, 69% of eligible Bupa employees and 67% of eligible Co-op employees were taking part.
- Balances. Across Bupa and the Co-op, average savings were £96 after four months and £170 after eight.
The strategy says the research indicates “no adverse effect on pension contributions.”
Small pots matter because many people have none. The FCA’s 2024 Financial Lives Survey found that 1 in 10 people had no cash savings, and another 1 in 5 had less than £1,000 to draw on in an emergency. The strategy also cites University of Bristol research linking £2,000 or more in savings to a 60% lower risk of a household falling behind with bills.
The announcement doesn’t mention interest rates. For how interest builds on savings in general, see how compound interest works.
By the numbers
48%SUEZ new joiners taking part
69%eligible Bupa staff by month four
£170average saved after eight months
Why so few employers offered it
The FCA says this is often down to worries about rules. Employers asked whether payroll saving could breach National Minimum Wage rules, count as a regulated activity that needs FCA authorization, or count as a financial promotion.
The FCA’s statement, published on 27 August 2025, answers each point. It says schemes “can be structured in a way that does not involve the employer carrying out a regulated activity,” particularly where money goes to the savings provider and is not kept by the employer.
On the minimum wage, the government now says it will work with businesses on a factsheet for employers. It has not been published yet.
Did you know?
Only 7% of UK employers offered payroll saving, per DWP figures cited by the FCA in 2025. Many worried it could breach minimum wage rules or need FCA authorization.
What to check before you join
This isn’t financial advice. These are the points the regulator itself flags, turned into questions you can ask your employer.
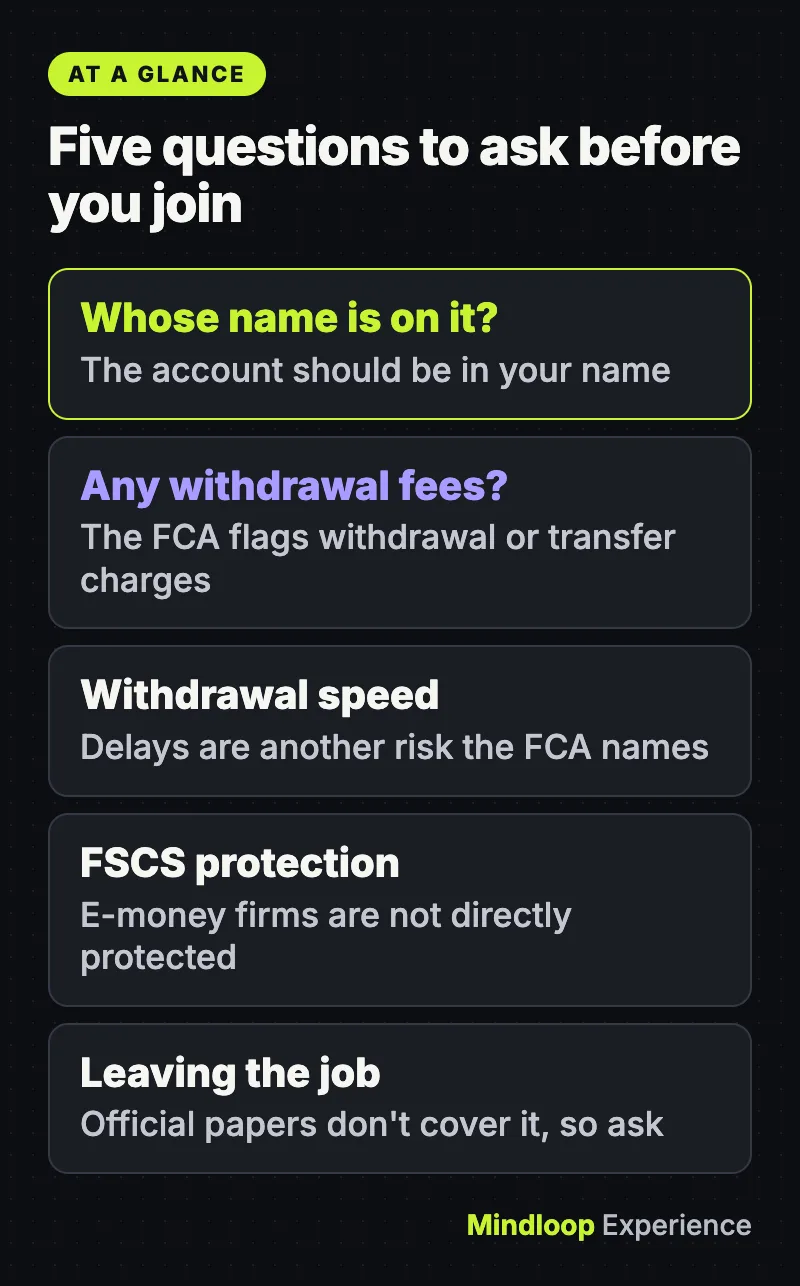
- Whose name is on the account? The FCA tells employers to avoid setups where the employer holds the money or the account is not in the employee’s name.
- Are there charges to get your money? The FCA lists withdrawal or transfer charges as a risk to avoid.
- How fast can you withdraw? Delays are another risk the FCA names.
- Is the provider FSCS-protected? The FCA says the FSCS may compensate customers if a savings provider fails, subject to eligibility and limits. Money held at e-money institutions is not directly protected.
- What happens if you leave the job? The official documents don’t cover this, so ask.
Cash savings can also lose buying power over time. Here’s how inflation works.
If your employer doesn’t offer one
Payroll saving only helps people whose employer takes part. The strategy points to another scheme for people on low incomes: Help to Save.
It is open to people receiving Universal Credit who had take-home pay of £1 or more in their last assessment period. You can save £1 to £50 a month, and the government adds a bonus of 50p for every £1 saved over four years.
Is there anything like this in the US?
Yes, in a different form. The US Department of Labor’s guidance explains that the SECURE 2.0 Act lets workplace retirement plans add a “pension-linked emergency savings account” for plan years starting after 31 December 2023.
Employee contributions are capped at $2,500, a figure that is indexed for inflation. Employers may enroll workers automatically at up to 3% of pay, and workers can opt out. Highly compensated employees are excluded.
Did you know?
The US has its own version: the SECURE 2.0 Act lets workplace retirement plans add a pension-linked emergency savings account, with employee contributions capped at $2,500.
Common questions
Is payroll saving the same as a workplace pension?
No. A pension is for retirement. Payroll savings are meant for emergencies and can be withdrawn at any time.
Do I have to join?
No. In an opt-in scheme you choose to sign up. In an opt-out scheme you are enrolled but can leave.
The bottom line
Payroll saving is a simple idea with trial evidence behind it, and more large UK employers now offer it. If yours does, ask the questions above before you sign up.
Quick quiz
What share of UK employers offered a payroll savings scheme, per DWP figures cited by the FCA?
- 48%
- 7%
- 69%
Department for Work and Pensions figures cited by the FCA in 2025 put it at 7% of UK employers.
Which sign-up design gave the highest participation in Nest Insight’s trials?
- Opt-in by paper form
- A bonus for early joiners
- Automatic enrollment with an opt-out
Nest Insight found participation was highest where staff were enrolled automatically and could opt out.
What does Help to Save add for every £1 saved over four years?
- A 50p bonus
- A £1 bonus
- A £50 bonus
The government adds a bonus of 50p for every £1 saved over four years.
Sources
Links last checked on 15 November 2026.
- GOV.UK, “Stronger savings for hundreds of thousands of workers” (14 November 2026)
- Financial Conduct Authority, Statement on workplace savings schemes (27 August 2025)
- HM Treasury, Financial Inclusion Strategy (5 November 2025)
- National Coalition for Workplace Savings
- GOV.UK, Get help with savings if you’re on a low income (Help to Save)
- US Department of Labor, FAQs: Pension-Linked Emergency Savings Accounts

Write a response