Index funds are the plain, low-cost way many people start investing, and you don’t need a big lump sum to own one. This explainer covers what an index fund actually is, how index mutual funds differ from ETFs and active funds, why a fee of 1% matters far more than it looks, and which tax-advantaged accounts US and UK readers can use. It ends with a short starter checklist. Every rule and limit below comes from the SEC, FINRA, the IRS, gov.uk, the FCA or the FSCS, and was checked on November 19, 2026. This is general information, not financial advice.
Key takeaways
- An index fund is a mutual fund or ETF that tries to match a market index instead of beating it.
- In the SEC example, a 1% fee leaves about $179,000 after 20 years versus about $208,000 at 0.25%.
- Clear high-interest debt and build an emergency fund before investing, then take any employer match.
- Use tax-advantaged accounts: a 401(k) or IRA in the US, a stocks and shares ISA in the UK.
What is an index fund?
A market index measures the performance of a basket of securities, such as the S&P 500 or the Russell 2000. You can’t buy an index directly. According to the SEC’s Investor.gov page on index funds, an index fund is “a type of mutual fund or exchange-traded fund that seeks to track the returns of a market index,” which gives you an indirect way to own the whole basket.
Some index funds hold every security in the index; others hold a sample. Many indexes are weighted by market capitalization, so the largest companies make up the biggest slices.
The key idea is the passive style. An index fund doesn’t try to beat the market; it tries to match it, so it buys and sells less often than an actively managed fund. The SEC’s glossary entry says passive management usually means lower trading costs, lower realized capital gains and lower fees than active funds. Note the word “usually.” Investor.gov is blunt that “not all index funds have lower costs than actively managed funds,” so you still have to check the actual fee.
Investor.gov also lists index-specific risks: less flexibility when prices fall, tracking error, and underperforming the index because of fees and trading costs.
Index mutual funds vs ETFs vs active funds
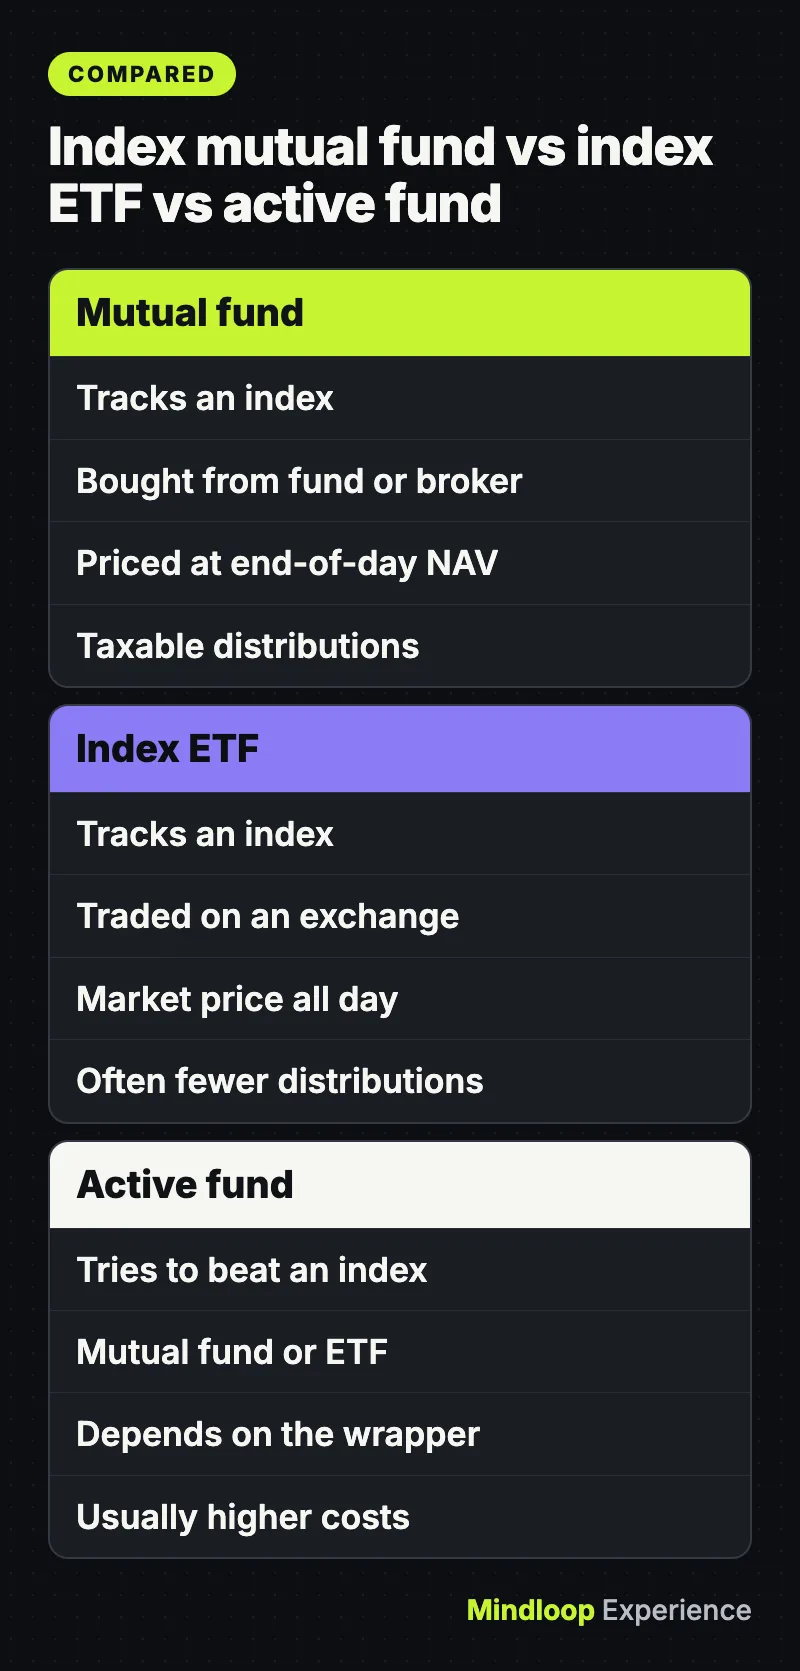
“Index fund” describes a strategy, not a wrapper. The same index can be tracked by a mutual fund or by an exchange-traded fund (ETF). The SEC’s April 2025 investor bulletin on mutual funds and ETFs sets out how the US versions differ:
| Feature | Index mutual fund | Index ETF | Actively managed fund |
|---|---|---|---|
| Goal | Match an index | Match an index | Beat or differ from an index |
| How you buy | From the fund or through a broker | Only on an exchange, through a brokerage account | Either, depending on the wrapper |
| Price you get | Net asset value (NAV), set at the end of each business day | Market price during the trading day, which can sit above or below NAV | Depends on the wrapper |
| Typical costs | Ongoing expenses; some charge sales loads or account fees | Ongoing expenses, plus any broker commission | Usually higher, because managers research and trade more |
| Taxes in a taxable account | Capital gains distributions are taxable | Often fewer distributions, thanks to in-kind exchanges | Frequent trading can mean more distributions |
Two details trip up beginners: you can’t always tell a fund’s type from its name (check the prospectus), and the ETF tax edge disappears inside a tax-advantaged account: “there is no tax difference between an ETF and a mutual fund if the investment is held in a tax-advantaged account (e.g., a 401(k) or IRA).”
The pricing and tax rules above are US-specific. UK readers will meet the same passive strategy inside unit trusts and investment funds, which gov.uk lists among what a stocks and shares ISA can hold (more on that below).
Why expense ratios matter so much
Every fund charges an ongoing yearly fee as a percentage of what you hold (the expense ratio). It comes out of the fund’s assets, so you never see a bill.
The SEC’s July 2025 bulletin, How Fees and Expenses Affect Your Investment Portfolio, runs a simple example: a $100,000 investment that grows 4% a year for 20 years. After 20 years, the portfolio would be worth:
- about $208,000 with a 0.25% annual fee
- about $198,000 with a 0.50% annual fee
- about $179,000 with a 1.00% annual fee
The gap is that large because a fee cuts your balance and also wipes out the returns that money would have earned. This is compound interest working against you.
To compare real funds, the SEC says to read the standardized fee table in every US mutual fund and ETF prospectus. FINRA’s Fund Analyzer lets you compare up to three funds and shows how their fees affect the value over time, using a return you choose. In the UK, compare both the fund’s own ongoing charges and any fee the account provider adds.
Did you know?
In the SEC’s example, the same $100,000 growing 4% a year for 20 years ends near $208,000 with a 0.25% fee but only about $179,000 with a 1% fee.
Diversification, risk and what isn’t insured
Diversification means spreading money across many investments so one failure doesn’t sink you. Investor.gov’s asset allocation guide sums it up as “Don’t put all your eggs in one basket,” and notes that funds make it easy to own a small piece of many companies. It also warns that a fund won’t necessarily diversify you “if it is narrowly focused.” A broad market index fund spreads risk across many companies; a fund tracking one sector, or a single stock, does not.
Diversification doesn’t stop the whole market from falling. The SEC’s ETF page states that funds “are not guaranteed or insured by the FDIC or any other government agency,” and “You may lose some or all of the money you invest.” Money you need soon doesn’t belong in stock funds.
Starting small: dollar-cost averaging and fractional shares
Dollar-cost averaging. Investor.gov defines it as “investing your money in equal portions, at regular intervals, regardless of the ups and downs in the market.” Because the amount is fixed, you buy more shares when prices are low and fewer when they’re high. If you contribute from every paycheck to a 401(k), you’re already doing it. Saving straight from your pay, as in our guide to payroll savings, uses the same habit.
Low minimums. The SEC bulletin notes that some mutual funds set relatively low minimum purchases, and ETF shares can often be bought for relatively low dollar amounts.
Fractional shares. Some brokers let you buy part of a share by dollar amount. FINRA’s guide to fractional shares lists the catches: availability varies by firm (some limit it to certain stocks or ETFs), you currently can’t transfer fractional shares to another broker without selling, you might not get voting rights, and the way a firm executes these orders can affect your price.
Where to hold index funds in the US
Tax-advantaged accounts let more of your return compound.
401(k) and similar workplace plans. If your employer matches contributions, an archived Investor.gov column suggests contributing at least enough to get the full match. Its example: an employer that adds 50 cents per dollar is “an immediate 50 percent return on your money.”
2026 limits (per the IRS announcement for 2026):
- 401(k), 403(b), governmental 457 and TSP employee contributions: $24,500, plus an $8,000 catch-up at 50 and over (a higher $11,250 catch-up applies at ages 60 to 63).
- IRA contributions: $7,500 across all your traditional and Roth IRAs combined, plus a $1,100 catch-up at 50 and over.
Roth IRA. The IRS Roth IRA page explains that you can’t deduct contributions, but qualified withdrawals are tax-free. Eligibility shrinks at higher incomes: the IRS 2026 release puts the Roth phase-out range at $153,000 to $168,000 for single filers and $242,000 to $252,000 for married couples filing jointly.
Looking ahead. On November 12, 2026, the IRS announced the 2027 limits: the 401(k) limit rises to $25,500 and the IRA limit stays at $7,500.
By the numbers
$24,5002026 401(k) employee limit
$7,5002026 IRA limit
$25,5002027 401(k) limit
Where to hold index funds in the UK
Stocks and shares ISA. Gov.uk’s guide to how ISAs work says you pay no tax on income or capital gains from investments inside an ISA. You can put in up to £20,000 in the 2026 to 2027 tax year (April 6 to April 5), in one account or split across several. Stocks and shares ISAs can hold company shares, unit trusts and investment funds, and bonds. You must be 18 or over. If you’ve read about a lower cash ISA cap: an October 2026 HMRC newsletter confirms the £20,000 cash ISA limit is being kept from April 2027 and the planned £12,000 cap will not take effect.
Lifetime ISA. Per gov.uk, you must open it and pay in before 40, can add up to £4,000 a year until 50, and the government adds a 25% bonus (up to £1,000 a year). It can hold cash or stocks and shares, and it counts toward your £20,000. The money is meant for a first home or for age 60 and over. Most other withdrawals before 60 carry a 25% charge on the amount you take out, bonus included.
Workplace pension. The FCA’s Should you invest? guide suggests paying regularly into your pension before making other investments.
FSCS protection. The FSCS can pay up to £85,000 per eligible person, per firm, if an FCA- or PRA-authorized investment firm fails after April 1, 2019 and your money or assets are short. It does not cover poor investment performance, and cover varies by product, so check before you invest.
Did you know?
A Lifetime ISA gets a 25% government bonus of up to £1,000 a year, but most withdrawals before 60 carry a 25% charge on the amount taken out.
Before you invest: a starter checklist
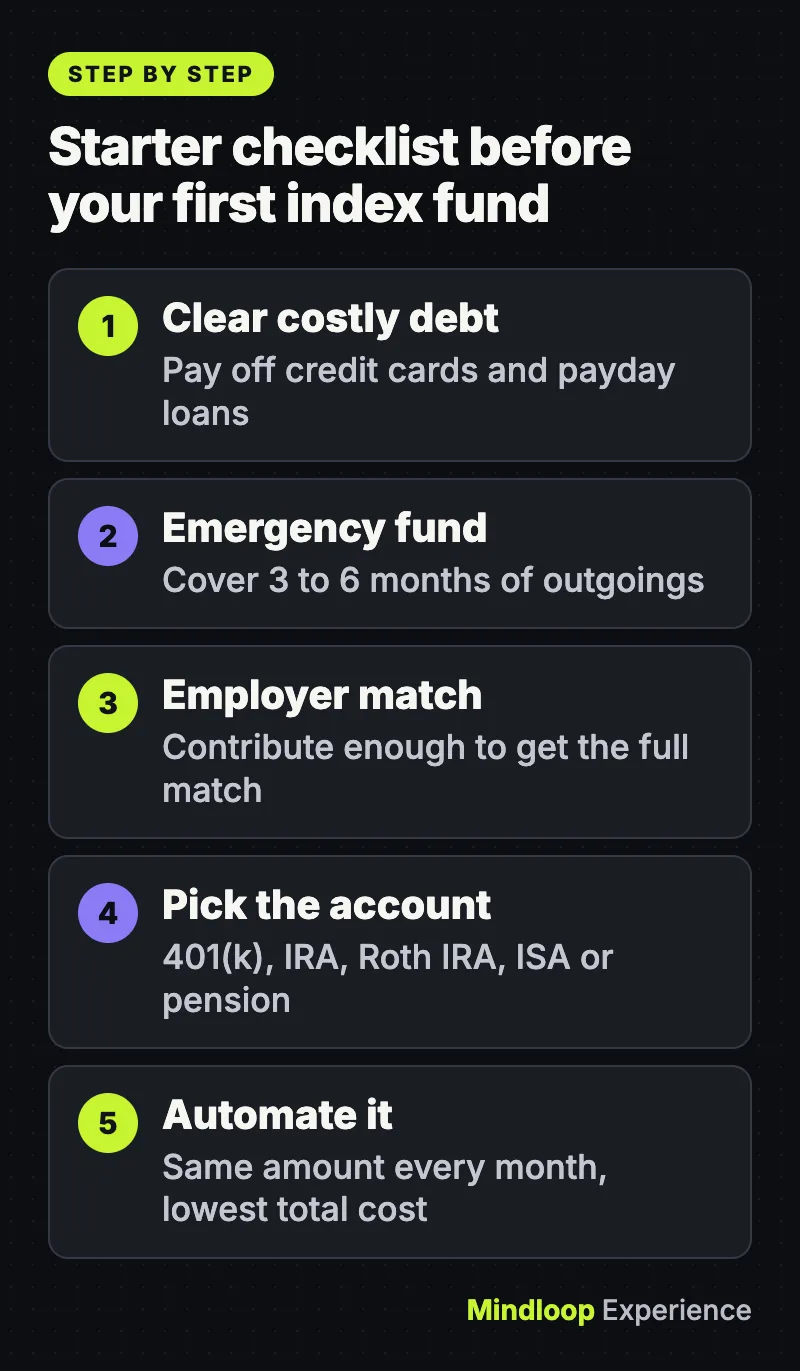
US and UK regulators put the same steps first. The FCA’s guide and Investor.gov’s page on paying off high-interest debt line up closely:
- Clear expensive debt. Investor.gov says “virtually no investment will give you returns to match an 18% interest rate on your credit card,” and applies the same advice to other high-interest debt (about 8% or above). The FCA says to pay off credit cards and payday loans first, and never to buy investments on a credit card.
- Build an emergency fund. The FCA notes that many experts suggest enough to cover 3 to 6 months of outgoings. Our guide on how to build an emergency fund shows how to get there on a tight budget.
- Take any 401(k) employer match (US) or keep up workplace pension contributions (UK).
- Pick the account (401(k), IRA or Roth IRA in the US; stocks and shares ISA, Lifetime ISA or pension in the UK).
- Compare total costs, meaning the expense ratio plus any account, platform or trading fees.
- Set a fixed monthly amount and automate it.
Common mistakes beginners make
- Assuming “index” means cheap. Investor.gov warns that not all index funds cost less than actively managed funds. Check the fee table.
- Mistaking a narrow fund for a broad one. A fund tracking one sector or theme doesn’t spread risk the way a total-market fund does.
- Falling for hype. The FCA’s scam warnings flag pressure to act fast, offers that sound too good to be true and “exclusive” deals. In the UK, check a firm on the FCA Firm Checker. Many scams start with an unexpected message or call, which our guide to spotting phishing emails, texts and scam calls covers.
- Ignoring inflation. Cash left idle for decades loses buying power, as our inflation explainer shows. The FCA makes the same point about savings held in cash.
When to get advice
Consider regulated professional advice if you have a large sum to invest, a complicated tax situation, or you’re unsure how much risk you can take. In the US, the SEC’s fee bulletin suggests asking any professional exactly how they’re paid and what every fee is. In the UK, the FCA says to check that a firm is authorized before you deal with it, and the FSCS says to confirm that the service is regulated and protected.
The bottom line
An index fund is a simple tool: own a slice of a whole market, pay as little as possible for it, and add to it regularly. The work is mostly in the order you do things: debt and emergency savings first, then any employer match, then the right tax-advantaged account, then the lowest total cost. For more on saving and borrowing, browse our Money section.
Frequently asked questions
How much money do I need to start investing in index funds?
There is no single minimum. The SEC notes that some mutual funds set relatively low minimums and ETF shares can often be bought for small amounts. Some brokers also sell fractional shares, though availability varies by firm and they can’t be transferred to another broker.
Are index funds safe?
Index funds spread risk across many companies, but they can still fall with the market. The SEC says funds are not guaranteed or insured by the FDIC or any other government agency, and you may lose some or all of the money you invest.
Is an index ETF better than an index mutual fund?
Neither is better for everyone. ETFs trade all day at market prices and often pay fewer taxable distributions, while mutual funds are priced once a day at NAV. Inside a 401(k) or IRA, the SEC says there is no tax difference between them.
Can I hold index funds in a stocks and shares ISA?
Yes. Gov.uk lists unit trusts and investment funds among what a stocks and shares ISA can hold. Income and gains inside the ISA are tax-free, and you can put in up to £20,000 in the 2026 to 2027 tax year.
Quick quiz
What does an index fund try to do?
- Beat the market every year
- Match the return of a market index
- Avoid all stock market losses
Investor.gov says an index fund seeks to track the returns of a market index.
In the SEC example, roughly what is $100,000 worth after 20 years with a 1% fee?
- About $179,000
- About $198,000
- About $208,000
The SEC bulletin shows about $179,000 at a 1% fee versus about $208,000 at 0.25%.
What is the 2026 UK ISA allowance?
- £4,000
- £12,000
- £20,000
Gov.uk says you can save up to £20,000 across your ISAs in the 2026 to 2027 tax year.
Sources
Links last checked on November 19, 2026.
- Investor.gov (SEC): Index Funds
- Investor.gov (SEC): Characteristics of Mutual Funds and Exchange-Traded Funds (ETFs), Investor Bulletin
- Investor.gov (SEC): How Fees and Expenses Affect Your Investment Portfolio
- FINRA: Investing in Fractional Shares
- IRS: 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500
- GOV.UK: Individual Savings Accounts, how ISAs work
- FSCS: Investments
- FCA InvestSmart: Should you invest?


Write a response